Материал: The international monetary system
2.3 Yuan
"Idealist buys euro realist - dollars, and
the truly wise man chooses the yuan." This phrase may have become in some
measure winged circulated among financial analysts, but today is used for
almost all those who somehow interested in keeping the money.is in good
climatic conditions, has a lot of cheap labor, and has a strong power to the
people with the ideas and the use of harsh measures in dealing with demographic
and economic issues. The country ranks first in the world in terms of
population, which amounts to more than 1.3 billion people. Residents of the
country are different discipline and hard work. Low wages and favorable
conditions for the functioning of enterprises in export processing zones, a
positive impact on the competitiveness of products, where producers from
developed countries to move production of labor-intensive goods. This
contributes to the specialization of the Chinese economy in the production of
series of industrial products. Industry plays an important role in the economy.
China is the largest exporter of industrial products in the world. Its share of
world exports is around 12%, surpassing the US and Japan.of experts converge.
Perhaps the West, more than 300 years holding in their hands the reins of world
economic processes of the Board, will relinquish the position of the rising
Eastern powers - China and the yuan will replace the dollar as the world's main
reserve currency within the next decade.yuan is the base unit of a number of
former and present-day Chinese currencies, and usually refers to the primary
unit of account of the renminbi, the currency of the People's Republic of
China. [1] It is also used as a synonym of that currency, especially in
international contexts - the ISO 4217 standard code for renminbi is CNY, an
abbreviation of “Chinese yuan”. (A similar case is the use of the terms
sterling and pound to designate the British currency and unit.)yuan (Chinese: 元; pinyin: yuán) is also known colloquially as a kuai (Chinese: 块; pinyin: kuài; literally: "lump"; originally a lump
of silver). One yuan is divided into 10 jiao (Chinese: 角; pinyin: jiǎo;
literally: "corner") or colloquially mao (Chinese: 毛; pinyin: máo "feather"). One jiao is divided into
10 fen (Chinese: 分; pinyin: fēn; literally: "small portion").symbol
for the yuan (元) is also used in Chinese to refer to the
currency units of Japan and Korea, and is used to translate the currency unit
dollar as well as some other currencies; for example, the US dollar is called
Meiyuan (Chinese: 美元; pinyin: Měiyuán; literally: "American yuan") in
Chinese, and the euro is called Ouyuan (Chinese: 欧元; pinyin: Ōuyuán; literally: "European yuan"). When
used in English in the context of the modern foreign exchange market, the
Chinese yuan (CNY) refers to the renminbi (RMB) which is the official currency
used in mainland China.1889, the Yuan was equated at par with the Mexican peso,
a silver coin deriving from the Spanish dollar which circulated widely in South
East Asia since the 17th century due to Spanish presence in the region, namely
Philippines and Guam. It was subdivided into 1000 cash (Chinese: 文; pinyin: wén), 100 cents or fen (Chinese: 分; pinyin: fēn), and 10 jiao (Chinese: 角; pinyin: jiǎo,
cf. dime). It replaced copper cash and various silver ingots called sycees. The
sycees were denominated in tael. The yuan was valued at 0.72 tael, (or 7 mace
and 2 candareens). [3]were issued in yuan denominations from the 1890s by
several local and private banks, along with the Imperial Bank of China and the
"Hu Pu Bank" (later the "Ta-Ch'ing Government Bank"),
established by the Imperial government. During the Imperial period, banknotes
were issued in denominations of 1, 2 and 5 jiao, 1, 2, 5, 10, 50 and 100 yuan,
although notes below 1 yuan were uncommon.earliest issues were silver coins
produced at the Guangdong mint, known in the West at the time as Canton, and transliterated
as Kwangtung, in denominations of 5 cents, 1, 2 and 5 jiao and 1 yuan. Other
regional mints were opened in the 1890s producing similar silver coins along
with copper coins in denominations of 1, 2, 5, 10 and 20 cash. [3] Other
regional mints were opened in the 1890s. The central government began issuing
its own coins in the yuan currency system in 1903. Banknotes were issued in
yuan denominations from the 1890s by several local and private banks, along
with banks established by the Imperial government.central government began
issuing its own coins in the yuan currency system in 1903. These were brass 1
cash, copper 2, 5, 10 and 20 cash, and silver 1, 2 and 5 jiao and 1 yuan. After
the revolution, although the designs changed, the sizes and metals used in the
coinage remained mostly unchanged until the 1930s. From 1936, the central
government issued nickel (later cupronickel) 5, 10 and 20 fen and ½ yuan coins. Aluminium 1 and 5 fen pieces were
issued in 1940.yuan is divided into 10 jiao which, in turn, are divided into 10
fen. There are coins in denominations of 1, 2, 5 fen.institution - the People's
Bank of China (instituted December 1, 1948).1994 to July 2005 the yuan was
tightly tied to the US dollar exchange rate of 8.28: 1.to the beginning of the
XX century the basic monetary unit in China was a silver liang of 10 and 100
maofenyam. For larger payments there were also silver ingots weighing up to 50
liang. In rural areas, were walking the ancient copper coins - tsyani, or
caches. Widespread have notes and coins of different foreign countries.began to
be produced in the form of silver coins in 1835. However, Liang continued to be
in circulation as currency. In lyanah numbered duties (until 1930) and taxes
(until 1933).1933 a law was passed on unification of the monetary system, but
it has not led to the establishment of a single currency. Still widespread
money had various foreign governments and local money.1935 in China actually
acted silver standard. China's currency fluctuated depending on the international
price of silver. On 15 October 1934 the yuan has departed from the value of
silver in the world market due to the establishment of duty on silver exported
from China.1935 was a monetary reform, silver yuan were withdrawn from
circulation and replaced by paper - "Fabi". It was announced on the
refusal of the silver standard and the transition to a currency based on gold,
but without a fixed gold content of the yuan. Excessive issue of paper money
led to inflation of the yuan.Reform in 1948 the gold content of the yuan was
established in 0,22217g pure gold and issued new paper money - "gold
yuan", which exchanged "Fabi" (3 million Fabi 1 "gold
yuan"). The official exchange rate to the US dollar was set at 4 "gold
yuan" to the dollar, but already 12 December 1948 it was devalued to
twenty per dollar.reunification areas liberated Communist People's Liberation
Army of China, there was a merger of local banks. In 1948 was created the
People's Bank of China. Withdrawn from circulation all local currency issued in
different liberated areas, and replaced with banknotes of the People's Bank of
China - renminbi (yuan).the founding of the PRC currency circulation has been
put under strict government control throughout the country. For each district
set the exchange rate of local money on the yuan, taking into account their
purchasing power and social status of their holders.June 1969 it was officially
announced the Latin name of the Chinese money - "Renminbi" (Renminbi
- "the people's money"), which is a unit of the yuan. Until 1974 the
yuan against foreign currencies was established mainly through the pound
sterling, as well as the Hong Kong dollar. Since August 1974 was introduced
daily quotation of RMB against the US dollar and other currencies on the basis
of a basket of currencies.1994, the Chinese authorities have preserved the yuan
exchange rate of $ 1/8.27 yuan. Recently, however, China is under increasing
pressure from the EU, Japan and the United States in particular, insisted on
the liberalization of the renminbi. According to them, the yuan is undervalued
and as a result of Chinese goods gain additional competitive advantage.2005,
China abandoned the peg of the yuan to the dollar and raised the rate of
national currency by 2%. The yuan will now be determined on the basis of its
relation to a basket of several currencies.to Chinese experts peg to a basket
of currencies will make the yuan more responsive to the global economic
situation, but it does not create a threat to the stability of the financial system.
By July 2008 the yuan gradually rose by 21.6% and from that time remains very
stable at 6,82-6,84 yuan per dollar. On 4 November 2009 the Russian currency
rate was 4.29 rubles per 1 yuan. On November 22, 2010 exchange rate of the
Russian currency was already 4.66 rubles per 1 yuan.to the World Bank, in 2003
the purchasing power of the yuan was approximately $ 1/1.8 yuan.
Chapter 3. Euro, Dollar, Yuan today and Scenarios on the Future of the International Monetary System
On the international currency market affect high dynamics and migration flows of capital. Changing factors that effecton the creation of the exchange rate and market structure. The exchange ratio is increasingly determined by the movement of financial flows, changes in rates of national currencies depend on the relative profitability of financial instruments. There is a coincidence and the estimated current exchange rate, which can be explained by the financial market close relationship with the real sector. This means that the market exchange rate, which is influenced by financial flows, also reflects the relative competitiveness of the national economy.the time the euro increased productivity in the US due to the inflow of capital in high-tech manufacturing and high economic growth stimulated by the rise in stocks and the dollar strengthened and its competitiveness. In 1999 became evident correlation between the dynamics of the dollar (and the euro) and the stock price index for US stock (European) market. All clearly seen growing role in shaping of the stock price of the dollar. The reason for this predominance of market shares in the market of government securities and changes in benefits residents.the turn of the millennium the United States remained the most attractive spheres of foreign capital, which directed most of the world flows. In 1999-2000, 62% of the capital exported from countries with positive current account balance went to the United States. In 1999 completed the establishment of the euro zone and the single currency was launched in non-cash transactions from the rate of 1/1.184 USD It had no significant impact on the inflow of foreign capital in the US, and the dollar continued to grow now in euros.addition to capital flows, exchange rates reflects the movement and outflow of capital from domestic markets, which reduces the exchange rate and therefore increases the rate on opposing currencies. In 1998-2000. there was a net outflow of capital from Europe, which contributed to the weakening of the euro in 2001 he continued. European and other investors continued to hope for a quick recovery of the US economy and the expansion of the financial market.investors bought a significant number of European shares, increased purchases of debt securities of the euro area, since the difference in yield between them and US securities declined.June 1999 in June 2000 the main feature of the global currency market was weakening of the euro against the dollar. During 2000-2001, the dollar continued to strengthen., the euro weakened. In 2001 US continued to absorb the lion's share of global capital flows.index of the dollar against the SDR for the years 1998-2000 rose by 7.5%, to 2001 another 3.5% due to higher net international demand for American assets. This happened despite a greater decrease in economic growth in US GDP than in other major countries. Despite the record current account deficit the US dollar held high, due to capital inflows, which stimulated the conviction that economic growth will resume, and corporate profitability will increase.2004 US economy there has been a decline in the dollar began to decline, despite the fact that the influx of foreign capital in the US in January 2004 reached its historical peak.this time, the position of the euro increasingly strengthened against the dollar.respect to our country, strengthening the position of the euro contributes to higher prices of goods imported from the EU.parallel with these processes is the growth of the yuan.course, the last 10 years, China's economy shows more than excellent results. From the point of view of economic power of the issuing country, the Chinese yuan has all the chances. However, things cannot happen so quickly, because, firstly, for what would make a currency reserve, it is necessary to lift restrictions on the convertibility and the Chinese currency is partially convertible. Second, the dollar is too much tied, including foreign exchange reserves in most countries.factor contributing to the prosperity of the yuan, is that the yuan is undervalued. Hence, the yuan has a chance to grow in the future. On 11.02.2012 the RMB exchange rate is about 16 US cents. The fact that the yuan is undervalued, talked for a long time. Despite the fact that the Americans did not like it and they demanded that China stop understate the rate of RMB, China, it was profitable, because he worked for export. Many economists, including representatives of the People's Bank of China, argue that a stronger yuan to China is not needed. Increasing the rate of the national currency, China will automatically reduce the competitiveness of their exports, which have a negative impact on the economy as a whole. Despite ultimatums Western countries, China will continue to adhere to its policy towards the national currency. Recent years have seen a gradual strengthening of the yuan against the dollar, but it is precisely the extent and pace of the theme that benefit the Chinese economy.late 2008, China announced its intention to make the yuan currency in trade settlements between the Chinese provinces of Yunnan and Guangxi and the member countries of ASEAN - Association of South-East Asia. And today there yuan has actually plays the role of reserve currency. Vietnam, Indonesia, and in other countries in Southeast Asia, people accumulate yuan, not dollars.should also be noted that Chinese banks are willing to give foreign companies cheap loans in RMB, the purpose of which is to spread the yuan over the world. So, they try to make the yuan relatively affordable and desirable currency trading, loans and as a result - make China a leader in the global financial market., not so long ago the authorities allowed a branch of China Bank of China in New York to take deposits in yuan. Now US investors can buy yuan for their needs. This is largely due to the internationalization of the yuan, China's wish to make the yuan popular currency.next point is the reduction of Chinese exports, against which the yuan can rise. The fact that today is not the best of times for the economy, export-oriented. China gradually begins to shift to the domestic market. If the state is set to export - it needs cheap national currency. If the domestic market, it is better to have an expensive currency. Consequently, the yuan will rise in value.to the results of World Economic Forum (6.2012) there are scenarios for the international monetary system in 2030 are as follows:
Reversion to Regionalism
Fiscal challenges in the Eurozone and the United States go unaddressed as policy-makers turn inward.global growth and decreased demand for exports make adjustments to China’s growth model more challenging, leading to stalling economic reforms.and financial flows decrease at the global level as countries increase their focus on regional economic ties.
Political deadlock and stagnating growth in Europe lead to a gradual disintegration of the European Monetary Union.reforms lead to a gradual unwinding of imbalances between the G2: the United States and China.high consumption in the United States and the growth of China’s consumer economy place pressures on natural resource sustainability.
Reconciling a Two-speed World
While Europe successfully reforms its economic
governance and emerges as a fiscal union, markets focus on the US’s
unsustainable fiscal situation.by strong growth, China actively pursues the use
of the renminbi (RMB) for trade among emerging markets.alternative monetary
order emerges with the RMB at its core, and questions emerge about how to
reconcile this two-speed world.scenarios are based on a series of strategic
conversations among industry, public policy and academic leaders from around
the world. They are not intended to be mutually exclusive predictions or the
only possible outcomes. They provide a tool to foster strategic thinking about
these challenges, to stretch the boundaries of what is perceived as possible
and to open up new avenues of potential solutions.UncertaintiesBusiness
Issuesection begins by explaining why uncertainties related to international
currencies create important challenges for businesses, and calls for an
assessment of possible alternative future developments of the international
monetary system.a globalized economy, an orderly international flow of money is
essential. If these flows are uncertain or prone to disruption, global
prosperity can be undermined. In recent years, the vulnerabilities of this
international monetary system have become increasingly apparent through
persistent global imbalances, instability within the Eurozone and a series of
increasingly global financial crises.international monetary system consists of
conventions, policies and institutions governing international payments, the
choice of exchange rate regimes and the supply of reserves. It creates an
environment where international currencies facilitate the exchange of goods and
services, the accumulation of savings, price setting and calibration as well as
the denomination of balance sheets for both public and private actors. It also
allows countries to run deficits in their external accounts and should ideally
contribute to a gradual rebalancing of these external positions.around the
smooth operating or expected outcomes of these functions can have significant
implications for business, in particular when exchange rate volatility affects
costs and prices. This may impinge on investment decisions and reduce
opportunities for growth and job creation - a dynamic playing out around the
world today. The possibility of micro - and macro-shocks makes medium - and
long-term planning more complex, in particular regarding revenue targets,
liquidity management and supply chains. Small and medium-sized enterprises are
particularly affected as they lack the resources multinational companies can
devote to complex treasury operations.Global Trade and Capital Integration with
Fragmented Economic Governancerapid global integration of trade and capital
flows over recent decades has been a key driver of global growth. World trade
almost tripled from the early 1990s to 2010, while international capital flows
increased almost five-fold over the same period (see Figures 1 and 2)
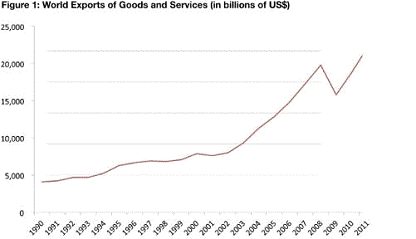
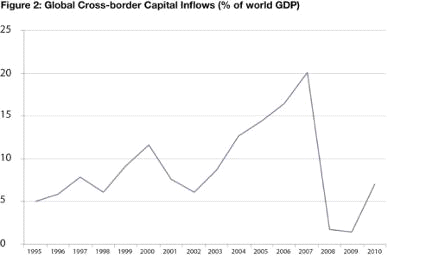
dynamics also fuelled the ongoing shift in
economic power towards emerging economies that have greatly benefited from the
opportunities of foreign investments, global supply chains and open capital
flows.this rapid integration of economic activities, global cooperation on
regulating these flows remains limited. The international monetary system
remains largely unchanged from its origins in a world that was significantly
less economically and financially integrated (see Appendix: Historical Overview
of the International Monetary System). Many observers believe this played a
role in fuelling the global financial crisis that began in 2008. The crisis
spurred an unprecedented degree of global coordination through the G20 process,
including a commitment from the French Presidency in 2011 to reform the
international monetary system. However, a focus on dealing with immediate
pressures, in particular stemming from Europe’s debt crisis, has since
overshadowed these global coordination and reform initiatives.economists and
policy-makers in the West argued that a free-floating regime of convertible
currencies would lead to automatic adjustments and the most efficient
allocation of resources at the global level. But developments over past decades
have not matched these expectations. Countries have not universally discarded
the management of exchange rates, and have often resorted to resolving domestic
economic challenges without regard for external impacts. This has led to an
accumulation of substantial macroeconomic imbalances that have left the
international monetary system increasingly fragile.is clear that given these
pressures, this system has to evolve. The widespread view is that the world is moving
towards a multipolar currency system based on the euro, dollar and yuan, in
which greater competition between reserve currencies would lead to greater
discipline to maintain the respective economies in balance. But the path to
such a system is highly uncertain. These currency areas, each of which could
serve as an anchor for global stability, face the need for significant internal
adjustments that constrain their international roles. This will be further
explored in the following section.World Economic Forum’s Euro, Dollar, Yuan
Uncertainties initiative is aimed at exploring challenging futures where
adjustments within the euro, dollar and yuan areas have a profound impact on
the evolution of the international monetary system. It builds on a series of
strategic conversations with leaders from the public, private and academic
sectors, exploring their most pressing concerns and uncertainties.purpose of
this report is not to advocate or predict specific outcomes. Rather, it
explores the critical uncertainties underlying the future international roles
of the euro, the dollar and the yuan, and depicts possible future states for
the international monetary system based on policy choices in each of the
currency areas. The year 2030 was chosen as a benchmark for these scenarios in
order to allow for significant structural adjustments to play out independently
from current political constraints.has remained relatively recently in the
quiet rivalry Western powers finally came out of the shadows and blooms before our
eyes. Cheap labor, goods and artificial restraint of the yuan exchange rate
played a role. China ranks second in the world in terms of GDP (2010) and the
first in terms of exports. China trade relations established with North
America, Japan, Western Europe and others. In the Republic of China focused a
lot of branches of foreign corporations. Although ten years ago the word
"China" and "low quality" were synonymous, it is now known
that in China there are products in all price categories. Thus, the exported
goods have including the highest standards of quality and in demand almost
everywhere, not to mention the share of Chinese textile and other consumer
goods in the markets of the world.conclusion, I would like to say that, most
likely, while talking about the yuan as a reserve currency is premature, given
that he is far from free convertibility and almost never used outside of the
Asia-Pacific region. But under certain conditions, it is quite possible in the
long term.is believed that the XXI century will be the century of China as the
new world economic center, and without Asian reserve currency that cannot be
achieved.
Conclusion
For many observers, this future is desirable. It
is, however, farfrom certain. Within each individual currency area, the necessaryadjustment
processes may play outsuccessfully, fosteringcontinued growth in the underlying
economy while alleviatingimbalances within the international monetary system.
But they mayalso play out in an unsuccessful manner, due either to a failure ofadjustments
to deliver continued growth or the pursuit of policiesthat serve domestic
interests at the expense of global stability.following section explores how
different combinations of moreor less successful adjustments within each
currency area coulddrive three very different scenarios for the international
monetarysystem in 2030. While these are not the only possible scenarios,they
reflect a range of views expressed by stakeholders overthe course of this
initiative and are intended to stimulate furtherdiscussionare scenarios?are
stories about the future. They represent relevant, plausible, challenging and
divergent possibilities, providing context around an issue for its
stakeholders. Scenarios are not predictions, preferences or forecasts.aim to
shift the focus away from preferences and the false security of predictability.
They are not predictive in terms of assigning any likelihood or probability to
individual scenarios.aim to raise awareness about the fact that opportunities
and risks in each scenario depend on the context, who is involved and how they
relate to the overall system. They are not normative in terms of depicting a
clear best - or worst-case scenario.aim to induce creativity in thinking about
these challenges and stretch the boundaries of what people perceive as
plausible futures for which to prepare. They are not exclusive in terms of
being the only possible futures.
Bibliography
1. http://studall.org/all-8060.html
2. "Capital Markets". Investopedia.
3. Jump up O'Rourke, Kevin H.; Williamson, Jeffrey G. (1999). Globalization and History: The Evolution of a Nineteenth-century Atlantic Economy. MIT Press. pp.1-. ISBN 978-0-262-65059-5.
. https: // en. wikipedia.org/wiki/United_States_dollar
. "The Breakup of the Euro Area by Barry Eichengreen:: SSRN". Papers. ssrn.com.14 September 2007. Retrieved 17 July 2011.
6. Jump up "Greek debt crisis: Straw says eurozone 'will collapse'". BBC.20 June 2011. Retrieved17 July 2011.
7. Jump up John Lanchester, "Euro Science," New Yorker, 10 October 2011.
8. Jump up "World’s Most Traded Currencies By Value 2012". http://www.investopedia.com/. Retrieved 10 June 2013. "Initial changeover (2002)". European Central Bank. Retrieved 5 March 2011.
9. Jump up "Exchange Rate Average (US Dollar, Euro) - X-Rates". X-rates.com. Retrieved2013-03-12.
10. Jump up "Global markets tumble on Spain, Italy worries".31 May 2012. [deadlink]
11. . Dollar, David, Kraay, Aart. "Trade, Growth, and Poverty". Finance and Development. International Monetary Fund. Retrieved 6 June 2011.
12. Eichengreen, B. (2010) “Exchange rate regimes and capital mobility: how much of the Swoboda thesis survives? ” in Charles Wyplosz (ed) “ The New International Monetary System” Routledge.
. Eichengreen, B. (2011), Exorbitant Privilege - The Decline of the Dollar and the Future of the International Monetary System, Oxford University Press, January.
15. Kregel, J. (2010), “An Alternative Perspective on Global Imbalances and International Reserve Currencies” - Economic Public Policy Brief Archive, Levy Economics Institute