Курсовая работа (т): Прогнозирование изменения цены акций
Некоторые недостатки, выявленные в процессе построения и проверки модели
могут послужить основой для дальнейших исследований.
Список литературы
1. Мантенья Р, Стенли Х. Введение в эконофизику: корреляции и сложность в финансах. -М. : ЛИБРОКОМ, 2009. -192 с.
2. Graham, Benjamin; David Dodd. The Intelligent Investor. (2003 edition). HarperCollins.
2. Graham, Benjamin. Security Analysis. (2003 edition). HarperCollins.
. Bob Litterman, Quantitative Resources Group. Modern investment management: an equilibrium approach. (2002 edition). The Wharton School, University of Pennsylvania.
. Luenberger D.G. Investment science. Stanford University Press.
. Bruce J. Feibel. Investment Performance Measurement. John Wiley & Sons Inc.
. Ramanna Vishwanath, Ramanna Vishwanath, Chandrasekhar Krishnamurti. Investment management. A modern guide to security analysis and stock selection. Springer Press.
. Tony Plummer. Forecasting Financial Markets: The Psychology of Successful investing (2008 edition). Kogan Page.
. W. Goeltzman. An Introduction to Investment Theory. Fisher Investments Press.
. Leigh Stevens. Essential Technical Analysis: Tools and Techniques to Spot Market Trends. John Wiley & Sons Inc.
. Farley Alan. Mastering short-term trading with technical analysis. Springer Press.
. Applebaum David. Levy processes and stochastic calculus. -Cambridge. : Cambridge University Press, 2009.
. Jorion Philippe. Financial Risk Management Handbook. -NJ. : Wiley, 2009.
. Peters Edgar. Fractal market analysis. -NJ. : Wiley, 1994.
. Viens Frederi. Modeling high-frequency data in finance. -NJ. : Wiley, 2012.
. Winkel Matthias. Levy process in finance. -Oxford. : Oxford University Press, 2010.
. Anderson, T. W.; Darling, D. A. Asymptotic theory of certain "goodness-of-fit" criteria based on stochastic processes // Annals of Mathematical Statistics. -1952. -№23.
. Carbone A., Castelli G., Stanley H.E. Time-dependent Hurst exponent in financial time series // Physica. -2004. №344.
. Eriksson Anders. The NIG distribution and the pricing of derivatives // University of North Carolina Working paper. -2009. -№1.
. Fan J., Wang Y. Multi-scale jump and volatility analysis for high-frequency financial data // Princeton University Working paper. -2007.
. Frain John. Value at Risk and the alpha-stable distribution // TEP Working Paper. -2008. -№0308.
. KitchenC. Normal Inverse Gaussian (NIG) Process With Applications in Mathematical Finance // The Mathematical and Computational Finance Laboratory. -2009.
. Laeven Roger, Cacho-Diaz Julio. Modeling financial contagion using mutually existing jump process // Princeton University Working paper. -2011. -
. Mantegna Rosario, Stanley Eugene. Scaling behavior in the dynamics of an economic index // Nature. -1995. -№376.
. Masoliver Jaume. A dynamical model describing stock market price distributions // Physica. -2000. -№283.
. Qian Bo. Hurst exponent and financial market predictability // University of Georgia Working paper. -2009. -№1.
. Reboredo J., Matias J. Nonlinearity on forecasting of high-frequency stock returns // Springer Science+Business Media. -2011.
. Robert Christian. A new approach for the dynamics of ultra high-frequency data: the model with uncertainty zones // Ecole Polytechnique Working Paper. -2009.
. Tisserand Marc. Exponential of Levy processes as a stock price // Humboldt University Working Paper. -2006. -№7.
. Wang B.H., Hui P.M. The distribution and scaling of fluctuations for Hang Seng index in Hong Kong stock market // The European physical Journal. -2001.
.
Ganapathy Vidyamurthy. Pairs Trading: Quantitative Methods and Analysis (Wiley
Finance) -2010.
Приложения
Приложение 1
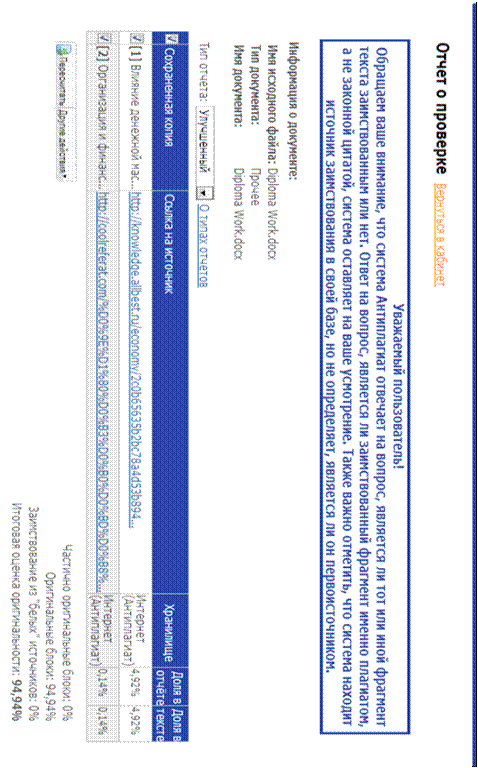
Приложение 2
Лист верификации авторства
Подтверждаю, что данная работа выполнена мною совершенно самостоятельно.
Студент группы № ____________________________________
(Ф.И.О.)
Работа проверена через систему antiplagiat.ru. Выявленный процент заимствований - ______ % текста.
Проверил ________________________________
(должность, звание, Ф.И.О.)
Дата
Приложение 3
Правительство Российской Федерации
Национальный исследовательский университет - Высшая школа экономики
_____________________________________________________________
факультет/отделение/подразделение
_____________________________________________________________
кафедра
Отзыв научного руководителя на БАКАЛАВРСКУЮ работу
Студента(ки)_________________________________________________ ,
Фамилия, имя, отчество
_______ курса, факультета _____________________________________
на тему: «____________________________________________________
___________________________________________________________»
Научный руководитель _____ ________________/подпись/___________
Дата
Приложение 4
ОТЗЫВ РЕЦЕНЗЕНТА
бакалаврской работы /магистерской диссертации
Студента ___________________________________ Курса __________
Руководитель________________________________________________
(Ф.И.О., ученая степень и (или) ученое звание)
Тема _______________________________________________________
________________________________ Подпись __________
(Должность, Ф.И.О. рецензента)