Материал: The_Future_of_Hydrogen-IEA-2020
The Future of Hydrogen Chapter 4: Present and potential industrial uses of hydrogen
|
|
|
|
Current |
|
|
2030 |
|
|
Long-term |
|
|
Low-carbon hydrogen supply |
|
|||
|
|
|
|
|
|
|
|
|
|
||||||||
|
Sector |
|
|
|
|
hydrogen |
|
|
|
|
|
|
|
|
|
||
|
|
|
hydrogen role |
|
|
|
|
demand |
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
Opportunities |
|
|
Challenges |
|
||||
|
|
|
|
|
|
demand |
|
|
|
|
|
|
|
||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
7% of primary |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
steel |
|
|
|
|
|
|
|
|
|
|
|
All options |
|
|
|
|
|
production |
|
|
|
|
|
|
|
|
Retrofit DRI |
|
|
|
|
|
|
|
|
|
|
|
|
|
Steel demand |
|
|
|
|
require higher |
|
||
|
|
|
|
takes place via |
|
|
|
|
|
|
|
facilities with |
|
|
|
||
|
|
|
|
|
|
|
|
|
keeps rising, |
|
|
|
|
production costs |
|
||
|
|
|
|
the direct |
|
|
|
|
|
|
|
CCUS. Around |
|
|
|
||
|
|
|
|
|
|
A doubling |
|
|
even after |
|
|
|
|
and/or changes |
|
||
|
|
|
|
reduction of |
|
|
|
|
|
|
30% of natural |
|
|
|
|||
|
|
|
|
|
|
under existing |
|
|
accounting for |
|
|
|
|
to processes. |
|
||
|
|
|
|
iron (DRI) |
|
|
|
|
|
|
gas can be |
|
|
|
|||
|
|
|
|
|
|
policies as the |
|
|
increased |
|
|
|
|
Direct |
|
||
|
|
|
|
route, which |
|
|
|
|
|
|
substituted for |
|
|
|
|||
|
|
|
|
|
|
DRI route is |
|
|
materials |
|
|
|
|
applications of |
|
||
|
Iron and |
|
|
requires |
|
|
|
|
|
|
electrolytic |
|
|
|
|||
|
|
|
|
|
used more, |
|
|
efficiency. 100% |
|
|
|
|
CCUS are usually |
|
|||
|
steel |
|
|
hydrogen. The |
|
|
|
|
|
|
hydrogen in the |
|
|
|
|||
|
|
|
|
|
relative to the |
|
|
hydrogen-based |
|
|
|
|
projected to have |
|
|||
|
production |
|
|
blast furnace |
|
|
|
|
|
|
current DRI |
|
|
|
|||
|
|
|
|
|
currently |
|
|
production could |
|
|
|
|
lower costs, |
|
|||
|
|
|
|
route |
|
|
|
|
|
|
route. Fully |
|
|
|
|||
|
|
|
|
|
|
dominant |
|
|
dramatically |
|
|
|
|
although these |
|
||
|
|
|
|
produces by- |
|
|
|
|
|
|
convert steel |
|
|
|
|||
|
|
|
|
|
|
blast furnace |
|
|
increase demand |
|
|
|
|
are highly |
|
||
|
|
|
|
product |
|
|
|
|
|
|
plants to utilise |
|
|
|
|||
|
|
|
|
|
|
route. |
|
|
for low-carbon |
|
|
|
|
uncertain. Long- |
|
||
|
|
|
|
hydrogen as a |
|
|
|
|
|
|
hydrogen as the |
|
|
|
|||
|
|
|
|
|
|
|
|
|
hydrogen in the |
|
|
|
|
term competition |
|
||
|
|
|
|
mixture of |
|
|
|
|
|
|
|
key reducing |
|
|
|
||
|
|
|
|
|
|
|
|
|
long term. |
|
|
|
|
from direct |
|
||
|
|
|
|
gases, which |
|
|
|
|
|
|
|
agent. |
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
electrification. |
|
||
|
|
|
|
are often used |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
on site. |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Virtually no |
|
|
|
|
|
|
|
Hydrogen from |
|
Hydrogen |
|||
|
|
|
|
|
9% increase |
|
|
|
|
any source could |
|
expected to |
|||||
|
|
|
|
dedicated |
|
|
|
|
|
|
|||||||
|
|
|
|
|
in high- |
|
|
|
|
replace natural |
|
compete poorly |
|||||
|
|
|
|
hydrogen |
|
|
Heat demand |
|
|
||||||||
|
|
|
|
|
temperature |
|
|
gas, e.g. in |
|
with biomass and |
|||||||
|
High- |
|
production for |
|
|
likely to rise |
|
|
|||||||||
|
|
|
heat demand |
|
|
industrial |
|
direct CCUS in |
|||||||||
|
temperature |
|
generating |
|
|
further, providing |
|
|
|||||||||
|
|
|
under existing |
|
|
clusters or near |
|
general, but may |
|||||||||
|
heat |
|
heat. Some |
|
|
an opportunity |
|
|
|||||||||
|
|
|
policies. No |
|
|
hydrogen |
|
prove |
|||||||||
|
(excluding |
|
limited use of |
|
|
for hydrogen if it |
|
|
|||||||||
|
|
|
additional |
|
|
pipelines. Blends |
|
competitive with |
|||||||||
|
chemicals |
|
hydrogen- |
|
|
can compete on |
|
|
|||||||||
|
|
|
hydrogen use |
|
|
with natural gas |
|
direct |
|||||||||
|
and iron and |
|
containing off- |
|
|
cost in the |
|
|
|||||||||
|
|
|
without |
|
|
are more |
|
electrification. |
|||||||||
|
steel) |
|
gases from the |
|
|
prevailing policy |
|
|
|||||||||
|
|
|
significant |
|
|
straightforward |
|
Full fuel switches, |
|||||||||
|
|
|
|
iron and steel |
|
|
environment. |
|
|
||||||||
|
|
|
|
|
policy |
|
|
but less |
|
or CCUS, tend to |
|||||||
|
|
|
|
and chemical |
|
|
|
|
|
|
|||||||
|
|
|
|
|
support. |
|
|
|
|
environmentally |
|
entail significant |
|||||
|
|
|
|
sectors. |
|
|
|
|
|
|
|||||||
|
|
|
|
|
|
|
|
|
|
|
beneficial. |
|
investment. |
||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||||
Hydrogen in oil refining
Oil refining – turning crude oil into various end-user products such as transport fuels and petrochemical feedstock – is one of the largest users of hydrogen today. Some 38 MtH2/yr, or 33% of the total global demand for hydrogen (in both pure and mixed forms), is consumed by refineries as feedstock, reagent and energy source. Around two-thirds of this hydrogen is produced in dedicated facilities at refineries or acquired from merchant suppliers (together called “on-purpose” supply). Hydrogen use is responsible for around 20% of total refinery emissions, and produces around 230 MtCO2/yr. Refineries’ existing large-scale demand for hydrogen is set to grow as regulations for sulphur content of oil products tighten. This provides a potential early market for hydrogen from cleaner pathways, which could lower the emissions intensity of transport fuels.
PAGE | 91
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
How does the refining sector use hydrogen today?
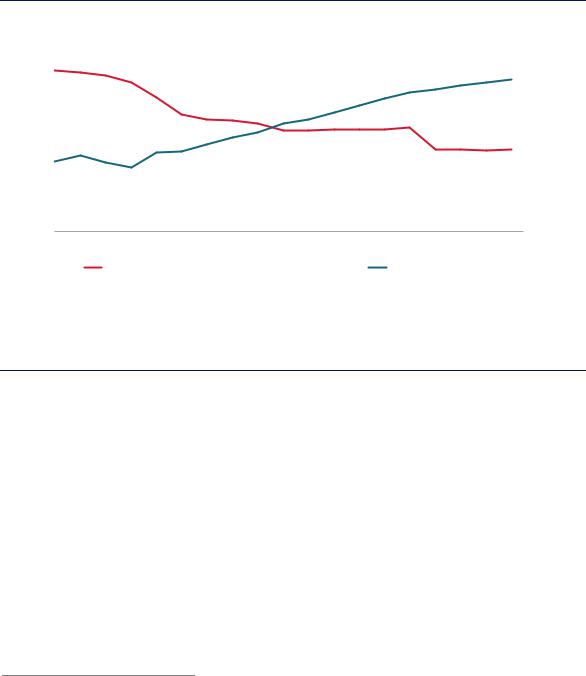
Hydrotreatment and hydrocracking are the main hydrogen-consuming processes in the refinery. Hydrotreatment is used to remove impurities, especially sulphur (it is often simply referred to as desulphurisation)23 and accounts for a large share of refinery hydrogen use globally. Today refineries remove around 70% of naturally incurring sulphur from crude oils. With concerns about air quality increasing, there is growing regulatory pressure to further lower the sulphur content in final products. By 2020 40% less sulphur will be allowed in refined products than in 2005 despite the continued growth in demand (Figure 33).
Figure 33. |
Allowed sulphur content in oil products |
|
|
|
|
|
||||||
per year |
25 |
|
|
|
|
|
|
|
|
|
|
110 |
|
|
|
|
|
|
|
|
|
|
|||
15 |
|
|
|
|
|
|
|
|
|
90 |
||
Milliontonnes |
|
|
|
|
|
|
|
|
|
|||
|
20 |
|
|
|
|
|
|
|
|
|
|
100 |
|
10 |
|
|
|
|
|
|
|
|
|
|
80 |
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
||
|
5 |
|
|
|
|
|
|
|
|
|
70 |
|
|
2005 |
2007 |
2009 |
2011 |
2013 |
2015 |
2017 |
2019 |
2021 |
2023 |
|
|
|
|
|
Allowed sulphur content in refined products |
|
Oil demand (right axis) |
|
|
|||||
Note: mb/d = million barrels per day.
Source: IEA (2018a), World Energy Outlook 2018.
mb/d
The quantity of allowed sulphur in refined products continues to decrease, while oil demand continues to increase.
Hydrocracking is a process that uses hydrogen to upgrade heavy residual oils into higher-value oil products. Demand for light and middle distillate products is growing and demand for heavy residual oil is declining, leading to an increase in the use of hydrocracking. In addition to hydrotreatment and hydrocracking, some hydrogen that is used or produced by refineries cannot be economically recovered and is burned as fuel as part of a mixture of waste gases.
The United States, the People’s Republic of China (“China”) and Europe are the largest consumers of hydrogen in refineries. The three regions represent around half of total refinery hydrogen consumption, reflecting the volume of crude oil they process and the stringency of their product quality standards.
Hydrogen is also used for upgrading oil sands and hydrotreating biofuels. For oil sands, the amount of hydrogen needed to remove sulphur from the raw bitumen varies considerably depending on the upgrading technology and the quality of the synthetic crude oil produced.
23 It also treats other chemical components – nitrogenand oxygen-containing compounds or metals – that are unfavourable to fuel quality and/or refining equipment, such as catalysts.
PAGE | 92
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
Overall around 10 kg of hydrogen is used per tonne of bitumen processed.24 The resulting synthetic crude oil still needs to be refined at a refinery, using hydrogen. For biofuels, hydrotreatment removes oxygen and improves the fuel quality of vegetable oils and animal fats processed into diesel substitutes. This process requires around 38 kg of hydrogen per tonne of biodiesel produced, but no further hydrogen is needed in subsequent refining steps.
Sources and costs of hydrogen for refinery use
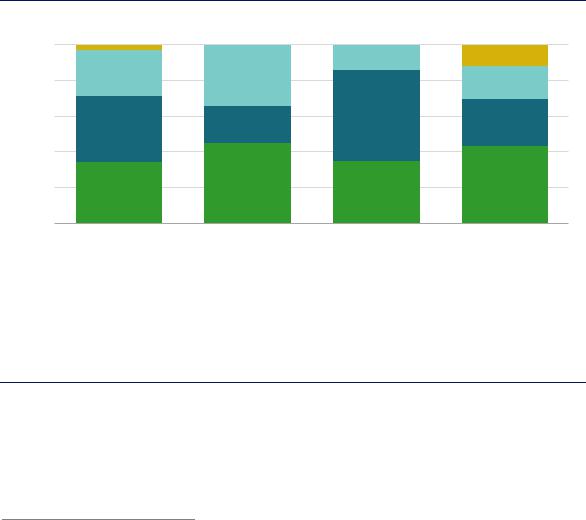
Globally, refinery hydrogen demand is met through the use of on-site by-products, dedicated on-site production, or merchant supply (Figure 34).
On-site by-product hydrogen comes largely from catalytic naphtha reforming, a process that produces high-octane gasoline blending components and generates hydrogen at the same time. Refineries with integrated petrochemical operations also derive by-product hydrogen from steam cracking. However, on-site by-product hydrogen is unable to fully cover refinery hydrogen demand, except in small refineries running on very low sulphur crude oils and with relatively low yields of road transport fuels. On average, on-site by-product hydrogen meets one-third of refinery hydrogen demand. The gap needs to be met, either by dedicated on-site production (about 40% globally) or procurement from merchant suppliers (around a quarter).
Figure 34. Sources of hydrogen supply for refineries in selected regions, 2018
100%
80%
60%
40%
20%
0%
World |
United States |
|
Europe |
|
China |
||||
|
|
Refinery by-product |
|
On-site SMR |
|
Merchant supply |
|
On-site coal |
|
|
|
|
|
|
|||||
|
|
|
|
|
|||||
Notes: SMR = steam methane reformer. For China, refinery by-product also includes hydrogen produced from refinery-integrated crackers.
Source: IEA 2019. All rights reserved.
Refinery hydrogen by-product covers only a third of hydrogen requirements, with the gap filled by dedicated on-site production and merchant supply.
Most dedicated on-site production uses natural gas feedstock, but light fractions of oil distillation and heavier feedstocks – petroleum coke, vacuum residues and coal – are also used in some regions. Use of heavier feedstocks is mostly restricted to India and China, where
24 Around 0.6 MtH2/yr is used to process 1 mb/d of bitumen.
PAGE | 93
IEA. All rights reserved.
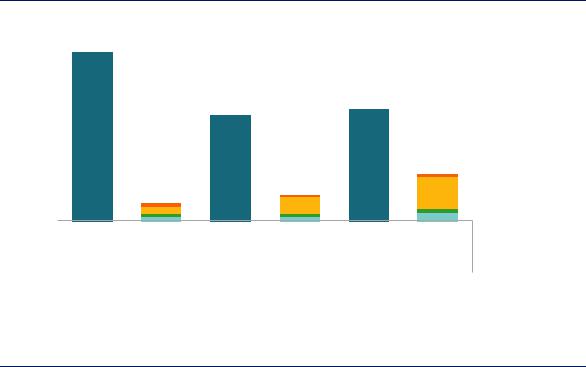
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
gas needs to be imported. Coal gasification is routinely included in new refinery setups in China as a main or auxiliary hydrogen production unit.
Merchant supply of hydrogen is an option in densely industrialised areas where developed hydrogen pipeline infrastructure exists, such as the US Gulf Coast and Europe’s Amsterdam- Rotterdam-Antwerp hub. As with dedicated on-site production, merchant hydrogen is mostly produced from natural gas, although a certain amount also comes from chemical processes, where it is a by-product of operations such as steam cracking and chlorine production. In regions such as the US Gulf Coast, merchant hydrogen can meet over a third of total hydrogen demand.
Hydrogen production costs vary widely, largely reflecting differences in natural gas prices. US production costs are among the world’s lowest, while costs are substantially higher in Europe and Asia. In the United States, hydrogen costs amount to around USD 1.1/kgH2 or USD 0.7 per barrel of oil refined. This may seem a relatively small cost component for refineries overall, for example in comparison with crude costs, but even a small cost advantage in hydrogen costs can have a notable impact on refining margins, which are generally thin in what is a very competitive market (Figure 35).
Figure 35. Hydrogen production costs compared to refining margins, 2018
barrelper |
8 |
|
|
|
|
|
CO2price |
|
|
|
|
|
|||
6 |
|
|
|
|
|
||
|
|
|
|
|
|
||
USD |
|
|
|
|
|
Fuel costs (gas) |
|
|
|
|
|
|
|||
|
|
|
|||||
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
4 |
|
|
|
|
|
OPEX |
|
|
|
|
|
|
||
|
|
|
|
|
|
||
|
|
|
|
|
|
CAPEX |
|
|
|
|
|
|
|
||
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
||
|
|
|
|
|
|
Average refining |
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
margin (2010-18) |
0 |
|
Refining |
Hydrogen |
|
Refining |
Hydrogen |
|
Refining |
Hydrogen |
|
|
|
|||||||
|
|
|
|
||||||
|
|
margin |
cost |
|
margin |
cost |
|
margin |
cost |
|
|
United States |
|
European Union |
|
|
Asia |
||
Note: Based on production costs via natural-gas based SMR. More information on the assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
In many regions, hydrogen costs are a significant drain on refinery profits.
Potential for future hydrogen demand in oil refining
In recent decades, refinery hydrogen demand has grown substantially as a result of growing refining activity and rising requirements for hydrotreating and hydrocracking. This trend is set to continue as fuel specifications globally further reduce acceptable levels of sulphur content. Many countries, including China, have already reduced sulphur content requirements in road transport fuels such as gasoline or diesel to under 0.0015%, and others may introduce similar standards. The International Maritime Organization has also introduced new bunker fuel regulations that limit the sulphur content of marine fuels to no more than 0.5% from 2020 (IEA, 2019a), and this is likely to lead to a significant increase in hydrogen requirements for marine
PAGE | 94
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
fuel production. However, hydrogen demand is also a function of inherent sulphur content in crude oils. The average quality of crude oil supply has been getting lighter and sweeter in recent years, due primarily to surging US tight oil output, and this is likely to moderate the need for hydrogen to some degree. Under current trends, overall hydrogen demand in refineries is set to grow by 7% to 41 MtH2/yr in 2030.
Beyond 2030 current trends and policies suggest the pace of hydrogen demand growth to slow down, as the scope to tighten product quality standards decreases and as oil demand for transport fuels is affected by a combination of efficiency improvements and electrification. Refiners are also likely to increase the efficiency of hydrogen recovery from waste refinery gases, lowering requirements for additional hydrogen production. Refinery hydrogen demand would decline in a scenario compatible with the objectives of the Paris Agreement, with the impact of declining oil demand more than offsetting that of higher hydrogen intensity.
Irrespective of the future trajectory of global energy demand, one common aspect is the dominant share of existing refineries in projected hydrogen demand. There is already sufficient refining capacity globally to fulfil the expected need for oil products. Together with the long lifetime of refineries, this limits the scope for substantial addition of new refining capacity. As a result, some 80–90% of cumulative on-purpose hydrogen supply (including both dedicated onsite production and merchant procurement) between today and 2030 would come from existing refineries in both scenarios (Figure 36).
Figure 36. Future hydrogen demand in oil refining under two different pathways
|
|
|
|
In line with current trends |
|
|
|
|
|
In line with the Paris Agreement |
|
|
|||||
/yr |
50 |
|
|
|
|
|
|
|
/yr |
50 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
2 |
|
|
|
|
|
|
|
|
2 |
|
|
|
|
|
|
|
|
MtH |
40 |
|
|
|
|
|
|
|
MtH |
40 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
30 |
|
|
|
|
|
|
|
|
30 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
20 |
|
|
|
|
|
|
|
|
20 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
10 |
|
|
|
|
|
|
|
|
10 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
0 |
|
|
|
|
|
|
|
|
0 |
|
|
|
|
|
|
|
|
2018 |
2022 |
2026 |
2030 |
|
2018 |
2022 |
2026 |
2030 |
||||||||
|
|
|
Refinery by-product |
|
On-purpose supply (existing refineries) |
|
|
On-purpose supply (new refineries) |
|
|
|||||||
|
|
|
|
|
|
|
|||||||||||
|
|
|
|
|
|
|
|||||||||||
Note: On-purpose supply refers to both dedicated on-site production and merchant procurement.
Source: IEA 2019. All rights reserved.
Future hydrogen demand in the refining sector comes mostly from today’s existing capacity.
Meeting future hydrogen demand in oil refining while reducing emissions
Hydrogen production – unless supplied as a by-product of refining operations – currently results in considerable CO2 emissions. Globally the production of hydrogen for use in refineries contributes some 230 MtCO2/yr emissions, which is around 20% of total refinery emissions.
PAGE | 95
IEA. All rights reserved.