Материал: The_Future_of_Hydrogen-IEA-2020

The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
of domestic HVC production in 2018. Methanol-to-aromatics, which is used to produce more complex HVC molecules, is currently still in the demonstration phase.
Unlike ammonia and methanol, HVCs – the precursors of most plastics – are produced mostly from oil products such as ethane, liquefied petroleum gas and naphtha. HVCs produced directly from oil products do not require hydrogen feedstock, but their production generates by-product hydrogen that can be used in oil refining and other chemical sector operations, such as the upgrading of other cracker by-products. Steam cracking and propane dehydrogenation processes for HVC manufacture produce around 18 MtH2/yr as a by-product globally. HVC demand is growing at a faster rate than refined oil product demand, which means that an increasing quantity of this by-product hydrogen could be available for use in other industries.
Chlor-alkali processes are another source of by-product hydrogen in the chemical sector, supplying around 2 MtH2/yr. While by-product hydrogen generated in the steam cracking process stems from oil products (mainly ethane and naphtha), the chlor-alkali process is a form of electrolysis (of brine) and is powered by electricity. Smaller volumes of by-product hydrogen are also produced from other processes such as styrene production.
How is demand for hydrogen likely to develop in future?
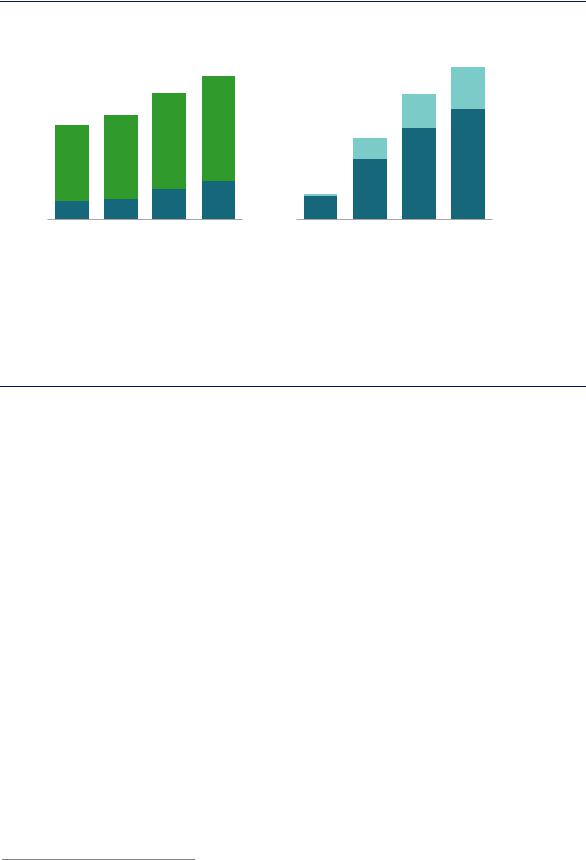
Demand for hydrogen for primary chemical production is set to increase from 44 Mt/yr today to 57 Mt/yr by 2030 as demand for ammonia and methanol grows (Figure 39).28 Demand for ammonia for existing applications is set to increase by 1.7% per year between 2018 and 2030 and to continue to rise thereafter. The share represented by demand for industrial applications grows more quickly during this period; that for nitrogen-based fertilisers is likely to start to plateau or even decline in many regions after 2030.
Demand for methanol for existing applications is set to grow at 3.6% per year between 2018 and 2030. The methanol-to-olefins/methanol-to-aromatics demand segment grows more quickly than the total, at 4.1% per year over the same period, with nearly all this growth coming from China. This rate of growth would require 19 MtH2/yr for methanol production for these existing applications by 2030, compared with 12 MtH2/yr today.
Together with energy efficiency measures, materials efficiency strategies are an important way of reducing emissions in IEA decarbonisation scenarios and could reduce these increases in demand (IEA, 2019b; Allwood and Cullen, 2012). Recycling and reusing plastics and other materials could reduce the amount of future primary chemical production required, although this would be likely to have a less pronounced impact on ammonia and methanol demand than on demand for other primary chemicals such as ethylene. Improving the efficiency with which fertiliser is used could also reduce future demand for chemicals. Specific policies have been announced in some countries to limit fertiliser use, such as the target for zero growth from current levels in China (Shuqin and Fang, 2018).
28 The most recent IEA publication exploring the future evolution of the chemical sector is IEA (2018b), The Future of Petrochemicals.
PAGE | 101
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
Figure 39. Hydrogen demand for primary chemical production for existing applications under current trends
/yr |
50 |
|
|
|
|
|
/yr |
25 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
2 |
|
|
|
|
|
|
2 |
|
|
|
|
|
|
|
|
|
MtH |
40 |
|
|
|
|
|
MtH |
20 |
|
|
|
|
|
|
|
Fertiliser |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
30 |
|
|
|
|
|
|
15 |
|
|
|
|
|
|
|
MTO/MTA |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
20 |
|
|
|
|
|
|
10 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Industrial |
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
10 |
|
|
|
|
|
|
5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
applications |
|
0 |
|
2000 |
2018e |
2030 |
2050 |
|
0 |
|
2000 |
2018e |
2030 |
2050 |
|
|
|
|
|
|
|
|
|
|
||||||||||
|
|
|
|
|
|
|
|
|
||||||||
|
|
|
|
Ammonia |
|
|
|
|
|
Methanol |
|
|
|
|
||
Notes: MTO = methanol-to-olefins; MTA = methanol-to-aromatics. Industrial applications for methanol include current fuel additive uses (e.g. methyl-tert-butyl-ether) and thermoset plastics (e.g. phenol formaldehyde). Industrial applications for ammonia include explosives (e.g. ammonium nitrate) and plastics (e.g. urea formaldehyde). Demand figures for 2030 and 2050 are consistent with those of the Reference Technology Scenario (IEA, 2018b), in which current trends are maintained. Data for 2018 are estimates based on previous years’ figures from the sources below.
Sources: IFA (2019), International Fertilizer Association Database; WoodMackenzie (2018), Methanol Production and Supply Database.
Hydrogen demand for ammonia and methanol for existing applications is set to rise.
Conversely, demand for ammonia and methanol could rise further if these chemicals were to become established as energy carriers for the transmission, distribution and storage of hydrogen, facilitating its use in new applications, or if they were to be used as fuels in their own right (see Chapters 2 and 3). If these new applications were to become widespread, the chemical sector could evolve to share the role that refineries play today in providing energy to downstream users.
Without any change in the current economics or regulation of production, current growth trajectories for chemical products are likely to lead to a growth in hydrogen production from natural gas and coal without the application of CCUS. Projecting forward current trends, this growth would cause total direct CO2 emissions from ammonia and methanol production to rise by around 20% between 2018 and 2030.
Meeting future hydrogen demand in the chemical sector while reducing emissions
The global production of ammonia and methanol currently generates CO2 emissions of around 630 MtCO2/yr.29 The global average direct emissions intensity of ammonia production is 2.4 tonnes of CO2 per tonne (tCO2/t), with average intensities for major regions in the range of 1.6–2.7 tCO2/t. New gas-based plants in the Asia Pacific region tend to be at the lower end of this range, whereas pure coal-based production (around 4 tCO2/t), widespread in China, constitutes the most CO2-intensive production route. For methanol the global average figure
29 This excludes the approximately 130 MtCO2/yr of concentrated CO2 streams that are separated and utilised to manufacture urea. A large proportion of this embedded CO2 is re-emitted in the agricultural sector when urea is applied to soils.
PAGE | 102
IEA. All rights reserved.

The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
is 2.3 tCO2/t, with average intensities for major regions in the range of 0.8–3.1 tCO2/t. As for ammonia, production based purely on coal is the most emissions-intensive pathway.
The production of HVCs is responsible for a further 250 MtCO2/yr of CO2 emissions. However, the key mitigation options currently under development (including the direct application of CCUS to existing process units, dry methane reforming and steam cracker electrification) do not involve additional dedicated hydrogen production. HVCs could also be produced from methanol, but this would similarly not involve additional hydrogen production beyond that required for the methanol. The focus in this section is therefore on ammonia and methanol.
Alternative process technologies and feedstocks could meet growing demand for large quantities of dedicated hydrogen feedstock in the chemical sector for ammonia and methanol while reducing CO2 emissions (Box 9). The three main cleaner process technology options are: using CCUS to reduce fossil fuel-related emissions (assuming sufficient CO2 transport and storage infrastructure is in place); using electrolysis-derived hydrogen (assuming a renewable electricity supply); and using biomass feedstocks (assuming a sustainable supply of bioenergy). Today all of these options are more costly than using fossil fuels without CCUS.
Box 9. Existing and planned low-carbon ammonia and methanol production
Three facilities in the United States were capturing CO2 from the production of hydrogen for ammonia-based fertilisers in 2018. In total, these operational plants have the capacity to produce over 150 ktH2/yr of low-carbon hydrogen and capture nearly 2 MtCO2/yr. The captured CO2 is currently fed into pipelines and used for EOR (IEA, 2016). By 2022 four similar projects are set to be commissioned. Two of these are in the United States, one is in Canada and one is in China, and all but one plan to sell the CO2 for EOR. EOR is likely to offer declining opportunities for use of CO2 in the long term (as oil production declines), and is not an option in all geographies. A further, larger project in south Western Australia is planned for operation by 2025, with a portion of the captured 2.5 MtCO2/yr coming from hydrogen production for ammonia fertiliser and destined for geological storage without EOR.
Since late 2018 Yara, the world’s largest ammonia producer, has been using by-product hydrogen from a steam cracker to reduce its consumption of natural gas (and a reported 10 ktCO2/yr of emissions) in an existing ammonia plant in the Netherlands (Brown, 2019). In collaboration with the energy company ENGIE, Yara is now assessing the feasibility of integrating electrolysis-based hydrogen into its operations in Australia (ENGIE, 2019). Feasibility studies are also being undertaken for electrolytic hydrogen projects in Chile (German Government, 2018) and Morocco (Fraunhofer IMWS, 2018). Work is also being undertaken in Iowa in the United States to produce ammonia using hydrogen from solar-powered electrolysis for use as a fertiliser and a fuel (Schmuecker Pinehurst Farm LLC, 2017), and there are similarscale research and pilot facilities in Oxford in the United Kingdom and Minnesota in the United States.
VärmlandsMetanol AB and ThyssenKrupp Industrial Solutions plan to commission the world’s first commercial-scale biomass gasification demonstration plant in Sweden to produce methanol
PAGE | 103
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
|
|
|
|
(VärmlandsMetanol AB, 2017). The process will use similar equipment to coal-based methanol production, currently widespread in China and being investigated as a prospect for substituting natural gas consumption in India (ET Energy World, 2018). Methanol is also being produced from biogas by BioMCN in the Netherlands (BioMCN, 2019) and from municipal solid waste in Canada (Enerkem, 2019). The Carbon2Chem, Steelanol and Vulcanol projects in Europe, and a Mitsui Chemicals project in Japan, seek to make use of the CO2 (and CO) from steel production and power generation to produce methanol, among other chemicals.
Sources: Brown (2019), “Ammonia plant revamp to decarbonize: Yara Sluiskil”; ENGIE (2019), “ENGIE and YARA take green hydrogen into the factory”; German Government (2018), “’Green’ hydrogen beckons for Chilean industry”; Fraunhofer IMWS (2018), “Fraunhofer IMWS and OCP Group sign Memorandum of Understanding”; Schmuecker Pinehurst Farm LLC (2017), Carbon Emission Free Renewable Energy; VärmlandsMetanol AB (2017), “In short about VärmlandsMetanol Ltd”; ET Energy World (2018), “Task force to study feasibility of making methanol from coal”; BioMCN (2019), “BioMCN produces methanol and bio-methanol”; Enerkem (2019), “Enerkem enables the chemical industry to achieve sustainability by recycling carbon from garbage”.
Using biomass for ammonia and methanol production looks significantly less cost-competitive than the other options (Figure 41), so the focus in the analysis in this section is on the use of natural gas with CCUS and on the use of electrolytic hydrogen.
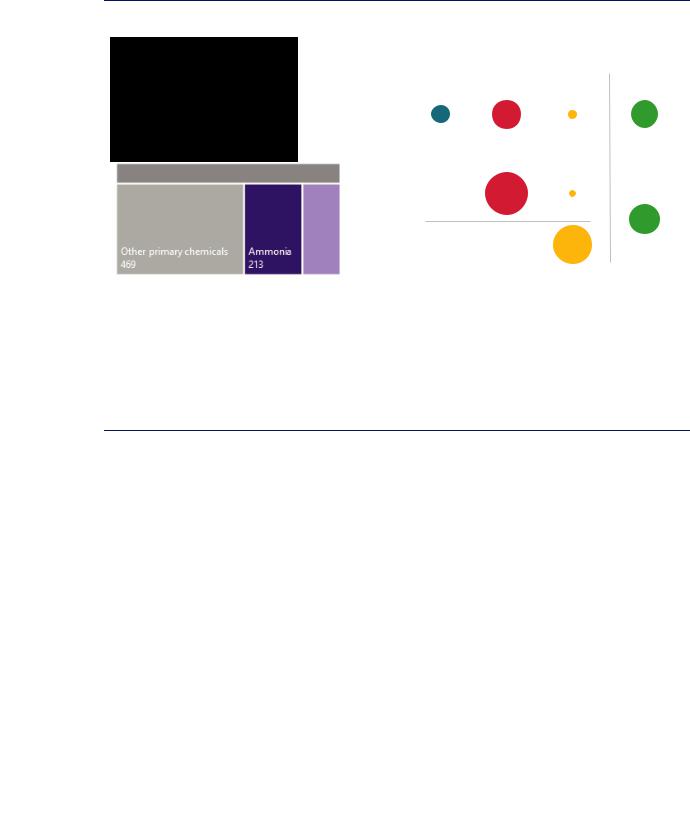
Meeting future ammonia and methanol demand entirely from these cleaner pathways would considerably increase demand for energy inputs to the chemical sector (Figure 40). If future demand in a Paris-compatible pathway were to be met entirely with hydrogen produced from natural gas with CCUS, around 320 bcm of natural gas would be required by 2030, nearly half of which would be used as feedstock. This is around 10% of global natural gas demand today. Around 450 MtCO2/yr would need to be captured, although around one-third of this could be used to produce urea. The largest carbon capture installations today are in the region of 1 MtCO2/yr. Capturing 450 MtCO2/yr by 2030 would require around 450 new projects of this size to be operational by this date, with a build rate of around 4 new projects per month between now and 2030.
If future demand were to be met entirely from low-carbon electrolytic hydrogen, this would require around 3 020 terawatt hours per year (TWh/yr) of additional electricity by 2030, equivalent to around 11% of today’s global electricity generation. It would also require 350– 450 GW of electrolyser capacity, depending on efficiency levels and capacity factors. The largest individual electrolysers currently under development are at the 100+ MW scale, meaning that 3 500–4 000 such installations would need to be constructed by 2030, or 6–7 per week between 2018 and 2030. Around 0.6 billion cubic metres per year (bcm/yr) of water would also be needed as feedstock for the electrolysers, which is around 1% of total water consumption in the energy sector today. Some 0.5 gigatonnes per year (Gt/yr) of oxygen would be produced as a by-product, which could be used in other industrial processes.
The electrolysis pathway would use some CO2 for the manufacture of urea (CH4N2O) and methanol (CH3OH).30 To avoid fossil fuel use in methanol synthesis altogether in 2030, 200 MtCO2/yr (or the equivalent amount of carbon monoxide, if available) would need to be
30 In the case of urea, this embedding of CO2 is only temporary, as it is re-released as the urea decomposes during application in the agricultural sector. For methanol the sequestering of the CO2 could theoretically be permanent, although many methanol applications today involve the carbon in methanol (and its chemical derivatives) being oxidised back to CO2 and released.
PAGE | 104
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
sourced and captured from biogenic (e.g. biomass gasification) or atmospheric (e.g. direct air capture) sources. A further 170 MtCO2/yr or equivalent would be required for urea.
In the absence of an economic source of biogenic or atmospheric CO2, it would still be beneficial to capture and utilise CO2 streams from unabated stationary point sources of CO2 (e.g. steel and cement production). These are likely to remain much cheaper in the short to medium term. However, the total emissions avoided would be much lower unless that CO2 would otherwise unavoidably have been emitted (Chapter 2). Geographically matching locations of low-cost renewable electricity, water availability and persistent CO2 sources that are not prohibitively expensive presents a significant challenge.
Figure 40. The implications of cleaner process routes for methanol and ammonia production
2018 |
649 Mt/yr |
Energy and hydrogen requirements for ammonia and methanol production |
2030 |
824 Mt/yr |
|
Methanol 142 |
|
|
|
Coal |
Gas |
Electricity |
Hydrogen |
|
|
(Mtoe) |
(bcm) |
(TWh) |
(Mt) |
|
Current |
53 |
171 |
|
44 |
|
technology |
132 |
||||
|
|
|
|||
|
|
|
|
NG w/CCUS |
323 |
|
|
85 |
56 |
|
|
|
Electrolysis |
3 020 |
56 |
Notes: NG = natural gas; w/ = with. Best practice energy performance used for 2030 natural gas estimates. 2030 electrolyser efficiency = 69% on an LHV basis. Demand figures for 2030 are consistent with those of the Clean Technology Scenario (IEA, 2018a), a scenario in which the goals of the Paris Agreement are achieved, including the implementation of materials efficiency strategies. Bubbles denoting energy and hydrogen requirements are sized on an LHV energy content basis. The hydrogen and energy quantities are equivalent, and not additive.
Source: IEA 2019. All rights reserved.
Satisfying the entire demand for ammonia and methanol through low-carbon production would require 323 bcm of natural gas paired with CCUS, or 3 020 TWh/yr of renewable electricity by 2030.
Cost competitiveness of cleaner pathways
Cleaner ways of producing ammonia and methanol have higher costs than those that are commercially available today. Production costs vary widely, however, between regions, depending on the costs of in each region of natural gas, coal, biomass and electricity (Figure 41).
PAGE | 105
IEA. All rights reserved.