Материал: The_Future_of_Hydrogen-IEA-2020
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
Using hydrogen to meet growing steel demand while reducing CO2 emissions
On average, producing one tonne of crude steel currently results in around 1.4 tonnes of direct CO2 emissions.37 Several cleaner pathways are under development that would significantly reduce CO2 emissions for primary iron and steel production (Box 10). These can be divided into two categories:
“CO2 avoidance” pathways seek to avoid most of the CO2 emissions entirely by adopting low-carbon sources of energy and reduction agents, usually using hydrogen.
“CO2 management” pathways aim to recover and manage the CO2 associated with traditional fossil fuel-based routes, usually via the direct application of CCUS.
Various projects are underway around the world to develop these processes towards commercialisation. These processes are generally at an earlier stage of development than those in the chemical sector described earlier in this Chapter.
Box 10. Projects for low-emissions steel production
CO2 avoidance pathways
HYBRIT. In Sweden SSAB (a steel producer), LKAB (an iron ore pellet manufacturer) and Vattenfall (a power company) formed the HYBRIT joint venture to explore the feasibility of hydrogen-based steelmaking, using a modified DRI-EAF process design (HYBRIT, 2019). Currently at pilot phase, the first commercial plant is expected in 2036. Of the SEK 1.4 billion (USD 147 m) estimated cost of the pilot plant, the Swedish Energy Agency will provide SEK 528 m (USD 56 m), with the joint venture partners contributing the rest.
SALCOS. Like the HYBRIT project, this collaboration between Salzgitter AG and the Fraunhofer Institute aims to partially implement hydrogen-based reduction of iron ore using the DRI-EAF route (SALCOS, 2019). While HYBRIT is aiming at virtually 100% hydrogen reduction from the outset, SALCOS will utilise a natural gas-fed process design and gradually increase the proportion of hydrogen.
GrInHy and H2FUTURE. These initiatives, both funded by the European Union's Fuel Cell and Hydrogen Joint Undertaking, aim to scale up emerging electrolyser designs to ensure that variable sources of renewable electricity can be utilised effectively in steel production and other industrial operations. The H2FUTURE project, co-ordinated by the Austrian utility VERBUND, is employing a 6 MW proton exchange membrane design (H2FUTURE, 2019), while GrInHy comprises a new reversible solid oxide cell unit (GrInHy, 2019). These projects started in 2016/17 and will conclude in the early 2020s.
Σiderwin and Boston Metal. Σiderwin is a research project initially funded by the European Union and now being taken forward by ArcelorMittal to pilot stage. It employs electrowinning
37 This does not account for emissions from captive utilities or subsequent uses of WAG, nor indirect emissions associated with centralised power generation. These, and several other factors, can substantially influence the emissions intensity.
PAGE | 111
IEA. All rights reserved.

The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
|
|
|
|
|
|
|
to produce steel (SIDERWIN, 2019). Boston Metal is a start-up venture that has recently attracted USD 20 million of investment to continue developing its molten oxide electrolysis process for producing a variety of metals (Boston Metal, 2019). Both of these processes utilise electricity directly for reduction, avoiding the need to produce hydrogen.
Ironmaking with ammonia. In Japan researchers have demonstrated the reduction of haematite (a constituent of iron ore) with ammonia at laboratory scale (Hosokai et al., 2011). If it can be demonstrated at commercial scale, this route could facilitate steel production in areas remote from those in which hydrogen (and ammonia) can be produced cheaply via lowcarbon pathways.
CO2 management pathways
HIsarna. Developed during the Ultra-Low Carbon Dioxide Steelmaking (ULCOS) research project funded by the European Union and several large steel producers, HIsarna is a demonstration-phase process for producing steel with significant potential for emissions reductions, especially if equipped with CCUS (HIsarna, 2019). The technology employs an upgraded smelt reduction process that processes iron ore in a single step, negating the need for coke ovens and agglomeration processes. Greenfield commercial plants could be available within 10 years of the completion of the current demonstration project.
DRI with CCUS. Al Reyadah, a wholly-owned subsidiary of Abu Dhabi National Oil Company, is capturing CO2 from a commercial-scale DRI-EAF plant operated by Emirates Steel (Al Reyadah, 2017). This post-combustion capture approach involves a chemical separation process that is more energy-intensive than that employed in the HIsarna process design, but benefits from the fact that the technology can be applied to existing equipment.
Chemicals from WAG. Several large pilot projects utilise the H2, CO and CO2 in WAG for various purposes. The climate benefit of these initiatives depends on the counterfactual considered, were they not to be used. The projects offer a variety of avenues to utilise a vast stock of existing steelmaking assets. Key examples include the public-private Carbon2Chem and Steelanol projects in Europe.
COURSE 50. This Japanese Iron and Steel Federation initiative seeks to raise the proportion of hydrogen used as a reduction agent in the BF-BOF route and to capture CO2 streams from blast furnace gas, with a full-scale demonstration planned in the 2030s (COURSE 50, 2019). The hydrogen is sourced from enriched and treated WAG streams. Together these modifications could lead to a 30% reduction in CO2 emissions per unit of steel produced.
Sources: HYBRIT (2019), “HYBRIT – towards fossil-free steel”; SALCOS (2019), “Project overview”; H2FUTURE (2019), “Production of green hydrogen”; GrInHy (2019), “Project overview”; SIDERWIN (2019), “Development of new methodologies for industrial CO2-free steel production by electrowinning”; Boston Metal (2019), “We transform dirt to metal very efficiently”; Hosokai et al. (2011), “Ironmaking with ammonia at low temperature”, Environmental Science & Technology; HIsarna (2019), “HIsarna: Game changer in the steel industry”; COURSE 50 (2019), “CO2 ultimate reduction in steelmaking process by innovative technology for cool earth 50”.
If, instead of following current trends, an alternative pathway were to be followed that aligns the future development of the energy sector with the goals of the Paris Agreement, the outlook for hydrogen demand and production in the sector could be very different. In such a pathway, the share of scrap recycling in total steel production is projected to grow more rapidly, from 23%
PAGE | 112
IEA. All rights reserved.

The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
today to 29% in 2030 and 47% in 2050, limited only by the availability of steel scrap. Our analysis suggests a slightly larger share of the gas-based DRI-EAF in primary steel production by 2030 (16%) in this case, and that progress on materials efficiency strategies would also be accelerated, leading to a reduction in the overall level of output.
Two parallel technological developments relating to DRI-EAF are also assumed to take place in this case. First, 30% of the natural gas consumed in DRI-EAF production would be replaced by 2030 by externally sourced pure hydrogen from electrolysis, which could be done without major equipment changes (Chevrier, 2018). Second, progress on developing the HYBRIT concept (Box 10) would be sufficient to demonstrate the first commercial-scale 100% hydrogen-based DRI-EAF plant by 2030, supplying 1.5 Mt/yr of crude steel, or 0.1% of total steel demand.
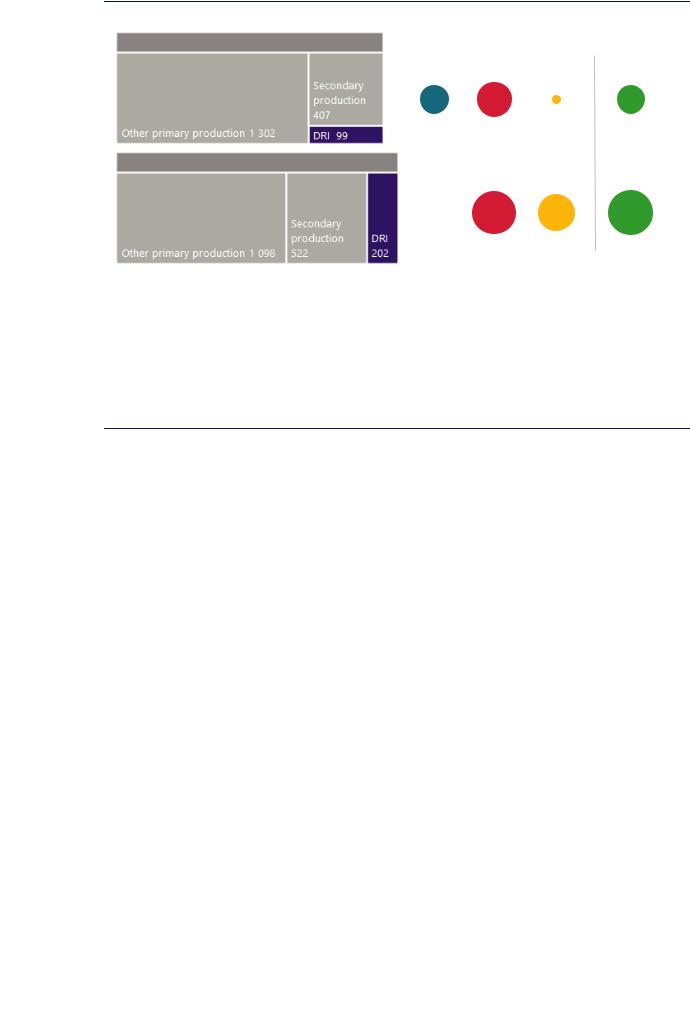
If these ambitious developments were to take place, hydrogen demand for iron and steel production would be 9–11 MtH2/yr by 2030 (the fourth column of Figure 44), similar to the level of 8 MtH2/yr expected on the basis of current trends. However, only around 4.5 MtH2/yr would be sourced from renewable electricity, with the remainder coming from natural gas. By comparison, under current trends all of the additional hydrogen demand would be met by natural gas without CCUS. This would require 230 TWh/yr of electricity, approximately equivalent to the total electricity consumption of Turkey today (Figure 45). Natural gas would nonetheless still play an important role in supplying the remaining hydrogen in 2030, resulting in 31 bcm/yr of natural gas demand, which is approximately equal to the natural gas consumption of Spain today. Coal-based DRI-EAF production would disappear by 2030 in this scenario, eliminating 12 Mtoe/yr, roughly the annual coal consumption of Mexico today.
In the long term a Paris-compatible pathway would seek to drastically reduce CO2 emissions from primary steel production.38 Using the 100% hydrogen DRI-EAF route for all primary steel production would largely eliminate CO2 emissions, provided the electricity was sourced from renewables. As Figure 12 shows, this would require 47–67 MtH2/yr (the fifth column of Figure 44). More than 2 500 TWh/yr of electricity would be needed to produce this much hydrogen, or roughly the combined electricity consumption of India, Japan and Korea today (Figure 45). A substantial but manageable amount of water would also be required as feedstock for electrolysers: around 0.6 bcm/yr, which is about 1% of total water consumption in the energy sector today. Some 500 Mt/yr of oxygen would be produced as a by-product; this could be put to use elsewhere in industry.
38 “CO2 emissions free” is not the same as being “carbon free”. Some carbon will continue to be required in the process of steelmaking, as it is a key chemical constituent of the final material.
PAGE | 113
IEA. All rights reserved.
The Future of Hydrogen Chapter 4: Present and potential industrial uses of hydrogen
Figure 45. Energy implications of fulfilling hydrogen demand via the DRI-EAF route
Total crude steel production 2018 |
1 809 Mt/yr |
|
Energy and hydrogen requirements for DRI-EAF |
|||
|
|
|
Coal |
Gas |
Electricity |
Hydrogen |
|
|
|
(Mtoe) |
(bcm) |
(TWh) |
(Mt) |
|
|
|
12 |
20 |
13 |
4 |
|
|
|
|
|
|
|
Total crude steel production 2030 |
|
|
|
|
|
|
1 821 Mt/yr |
|
|
|
|
||
|
|
|
|
31 |
230 |
10 |
|
|
|
|
|
|
|
Notes: Only the energy and hydrogen requirements for the commercial coal/gas-based and 100% hydrogen-based DRI-EAF routes are included. Demand figures are consistent with a scenario in which the goals of the Paris Agreement are achieved, including the implementation of materials efficiency strategies and maximum deployment of the secondary production route. Average hydrogen requirements for both the gasand 100% hydrogen-based DRI-EAF routes are assumed in calculating the hydrogen requirements and energy inputs. Bubbles denoting energy and hydrogen requirements are sized on an LHV energy content basis. The hydrogen and energy quantities are equivalent, and not additive. 95% DRI charge to the EAF is assumed in all cases. Current DRI-EAF facilities often operate with a higher share of scrap, as this lowers costs. More information on the assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
While the role of hydrogen could expand dramatically in the medium to long term, gas would continue to play an important role even after 2030 while the shift took place.
Cost competitiveness of cleaner pathways
In the absence of sufficiently high CO2 prices to trigger a switch to low-carbon hydrogen, replacing unabated natural gas with renewable hydrogen in the DRI-EAF route would widen the difference in cost between the commercial DRI-EAF and BF-BOF routes (Figure 46). Energy and other raw material input costs represent upwards of about 45% of production costs for the DRI-EAF routes, so small price differences can make a big difference to cost competitiveness. Whereas the range of gas prices today makes the commercial DRI-EAF route competitive with the BF-BOF route in specific instances, the hydrogen-based DRI-EAF route, based on current estimates of key technology parameters, would only be competitive in those places with the lowest electricity prices. It would also be significantly more expensive than its natural gas-based counterpart (15–90% more), even if natural gas production involved CCUS (10–85% more).
Among the other low-emissions pathways for steel production currently being explored, the “oxygen-rich smelt reduction BOF with CCUS” (HIsarna) route appears to have the lowest overall production costs in most regions in the current energy price context. According to the limited techno-economic information currently available in the public domain, it is less capital-intensive even than today’s commercial BF-BOF route, and could reduce direct CO2 emissions by around 80–90%. In most regions, the family of “CO2 management” pathways tends to be at a more advanced stage of development today. In the context of a long-term Paris-compatible pathway, however, the HIsarna design would have to be deployed in conjunction with a widespread CO2 transport and geological CO2 storage infrastructure.
Another key consideration, which is not explored in Figure 46, is the stock of existing capacity. Despite recent efforts to decommission underutilised assets, the steel industry still
PAGE | 114
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 4: Present and potential industrial uses of hydrogen |
suffers from overcapacity, and the market remained fragile in 2018 (OECD, 2019). Furthermore, the BF-BOF route accounts for around 90% of existing primary capacity, an asset class in which steel producers are generally not anticipating substantial greenfield investments in the coming years. With many facilities utilising this technology having been constructed in the past 10–20 years, it is going to be difficult for new alternative production routes to outcompete them without policy intervention. These dynamics underpin the development of CO2 management pathways (Box 10), which generally seek to reduce emissions while making use of existing integrated steel facilities. HIsarna is an exception to this as it requires greenfield investment.
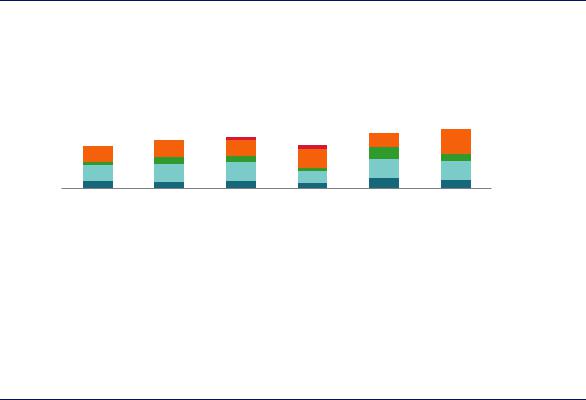
To compete in the long term with its natural gas-based counterpart equipped with CCUS, the 100% hydrogen-based pathway currently looks likely to need low-carbon electricity prices in the range of USD 5–35/MWh (Figure 47). This translates into hydrogen costs of USD 0.7– 2.0/kgH2, assuming electrolysers with high efficiencies and low CAPEX requirements. As discussed in Chapter 2, these costs may be realistic in certain regions when using dedicated low-cost renewable resources, but are challenging to achieve elsewhere. Moreover, regions with low-cost renewables resources may involve extra costs if they are not endowed with sufficient reserves of iron ore and other materials, and if they are located far from centres of demand.
Figure 46. Estimated costs of steel for selected greenfield production routes in 2018
(USD/t) |
1 250 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Range |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
cost |
1 000 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CCUS costs |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
750 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
Levelised |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Feedstock |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
500 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Fuel |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
250 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Fixed OPEX |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CAPEX |
|
|
0 |
|
BF-BOF |
DRI-EAF |
DRI-EAF |
|
Oxy. SR-BOF |
|
100% hydrogen |
50% hydrogen |
|
|
|||||||||
|
|
|
|
|
|
||||||||||||||||
|
|
|
|
|
|
||||||||||||||||
|
|
|
|
|
|
|
|||||||||||||||
|
|
|
|
|
|
|
|||||||||||||||
|
|
|
|
|
|
|
|
||||||||||||||
|
|
|
|
|
|
|
|
|
w/CCUS |
|
w/CCUS |
|
DRI-EAF |
DRI-EAF |
|
|
|
||||
|
|
|
|
|
|
|
|
|
|
|
|
|
(HIsarna) |
|
(HYBRIT) |
|
|
|
|
|
|
|
|
|
|
|
|
Commercial |
|
|
|
|
Demo |
|
Pilot |
|
|
|
|||||
Notes: Oxy. SR-BOF = oxygen-rich smelt reduction. CCUS costs includes the costs of capturing, transporting and storing CO2. Range refers to the range of total levelised costs across regions, with the lower end of the range disaggregated for each technology. An availability factor of 95% is applied to all equipment and an 8% discount rate is used throughout. It is assumed that the electrolysis route is supplied with 100% renewable electricity. Natural gas-based and 100% hydrogen-based DRI-EAF considers 95% DRI charge to the EAF. More information on the assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
The hydrogen-based DRI-EAF route is between 10% and 90% more costly than its natural gas-based counterpart, and is highly sensitive to the cost of electricity.
From a policy perspective, there are two key areas where support is needed to bolster the sustainable adoption of hydrogen as a reduction agent in the iron and steel sector. First, support is needed for demonstration projects that seek to scale up the 100% hydrogen-based DRI-EAF process; this could, for example, take the form of access to low-cost financing for increasing scales of demonstration, and funding to supporting the specific aspects of research and development (R&D) required to accelerate development.
PAGE | 115
IEA. All rights reserved.