Материал: The_Future_of_Hydrogen-IEA-2020
The Future of Hydrogen |
Chapter 2: Producing hydrogen and hydrogen-based products |
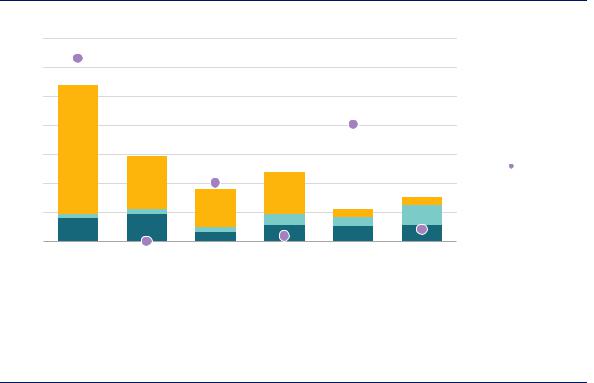
Figure 15. Hydrogen production costs in China today
USD/kgH2
7
6
5
4
3
2
1
0
Grid electricity Renewable |
Natural gas Natural gas |
Coal |
Coal with |
electricity |
with CCUS |
|
CCUS |
35 |
2 |
|
|
30 |
/kgH |
|
|
2 |
|
|
|
25 |
kgCO |
|
Fuel costs |
|
|
||
|
|
20 |
|
OPEX |
|
||
|
||
|
|
|
15 |
|
CAPEX |
|
||
|
||
|
CO intensity |
|
|
|
|
10 |
|
|
5 |
|
|
0 |
|
|
Notes: CAPEX of coal with CCUS = USD 1 475/kWH2. Renewable electricity costs = USD 30/MWh at 4 000 full load hours. More information on the underlying assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
Coal-based hydrogen with CCUS is likely to remain the lowest-cost clean hydrogen production route in China for the near term.
Reducing the carbon footprint will be a critical factor for the prospects of coal-based hydrogen in a low-carbon context. Adding CCUS to coal-based hydrogen production is expected to increase CAPEX and fuel costs by 5% and OPEX by 130%. In China and India, with their established coal mining infrastructure and the lack of availability of cheap domestic natural gas, coal-based hydrogen equipped with CCUS is likely to be at least in the medium term the cheapest option for clean hydrogen production.
Hydrogen from biomass
Hydrogen can be produced from biomass in different ways. In biochemical routes, microorganisms work on organic material to produce biogas (a process referred to as anaerobic digestion) or a combination of acids, alcohols and gases (fermentation). Thermochemical gasification of biomass is a process that works much like coal gasification to convert biomass to a mix of carbon monoxide, CO2, hydrogen and methane. Anaerobic digestion to produce biogas is the most technically mature of these processes, but can only process sewage sludge, agricultural, food processing and household waste, and some energy crops. Fermentation can process the non-edible cellulosic part of some plants. Gasification could potentially convert all organic matter, and in particular the lignin component of biomass. Although there are a number of biomass gasification demonstration plants in the world, the technology is not yet fully developed, and the problem of the formation of tars that may cause catalyst poisoning has not been fully resolved yet (Ericsson, 2017). In all cases, the produced gas would need to be further processed to extract hydrogen.
The complex processing of biomass means that it is generally a more expensive way of producing low-carbon hydrogen than solaror wind-based electrolysis. The potential for largescale biomass-based hydrogen production is also be limited by the availability of cheap biomass. For example, satisfying a theoretical hydrogen demand of 60 MtH2 in the US market –
PAGE | 51
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 2: Producing hydrogen and hydrogen-based products |
corresponding to four times the United States’ current hydrogen demand – would require almost 100% of its technical biomass potential, but only 6% of its wind power, and less than 1% of its solar power potential (Ruth, Jadun and Pivovar, 2017). Combining hydrogen production from biomass with carbon capture and storage could, however, be an option to create so-called “negative emissions”, which may have a role to play in the future.11
Comparison between alternative hydrogen production pathways
In the near term – that is, until 2030 – the cost advantage of fossil fuels is likely to continue in most places, with hydrogen from natural gas without CCUS costing in the range of USD 1–2/kgH2, depending on local gas prices.12
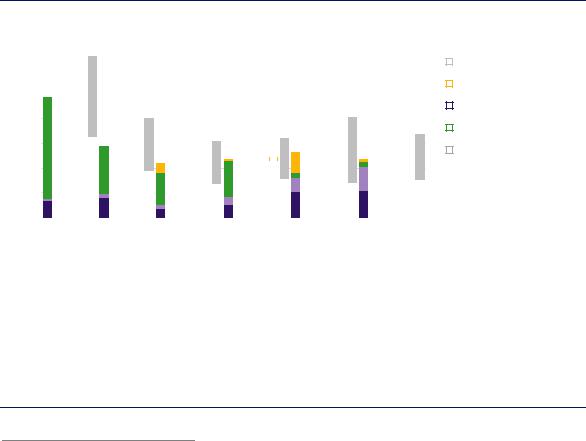
Except in the case of hydrogen produced from coal, fuel costs are the biggest single component of hydrogen production costs (Figure 16). Future hydrogen costs will therefore largely be influenced by electricity and gas costs, or parameters influencing these costs such as conversion efficiencies. Electrolysis production costs can also be sensitive to CAPEX requirements, in particular if plants are operating at low full load hours.
Figure 16. Hydrogen production costs for different technology options, 2030
2 |
7 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
USD/kgH |
6 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Combined sensitivity |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CO price sensitivity |
|
|
5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CAPEX and OPEX sensitivity |
||
|
4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Fuel cost sensitivity |
||
|
3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
WACC sensitivity |
||
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CO price |
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Fuel costs |
||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
0 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
OPEX |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|||
|
|
Electrolysis |
Electrolysis |
|
Natural gas |
|
Natural gas |
Coal without |
|
|
|
Coal with |
|
|
CAPEX |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|
|
|
|
|
grid |
renewable |
without CCUS |
|
|
with CCUS |
|
|
|
|
CCUS |
|
|
|
|
CCUS |
|
|
|
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Notes: WACC = weighted average cost of capital. Assumptions refer to Europe in 2030. Renewable electricity price = USD 40/MWh at 4 000 full load hours at best locations; sensitivity analysis based on +/-30% variation in CAPEX, OPEX and fuel costs; +/-3% change in default WACC of 8% and a variation in default CO2 price of USD 40/tCO2 to USD 0/tCO2 and USD 100/tCO2. More information on the underlying assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
In the near term, hydrogen production from fossil fuels will remain the most cost-competitive option in most cases.
11By combining the use of bioenergy and CCUS, CO2 formed during bioenergy conversion processes can be captured and injected into long-term geological storage. This provides the possibility to effectively remove CO2 from the atmosphere while producing energy.
12Just taking into account the LHV energy content of 1 kgH2, i.e. ignoring any later uses of hydrogen, a cost of USD 1/kgH2 corresponds to USD 30/MWh, or in barrels of oil equivalent to almost USD 50 per barrel (bbl).
PAGE | 52
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 2: Producing hydrogen and hydrogen-based products |
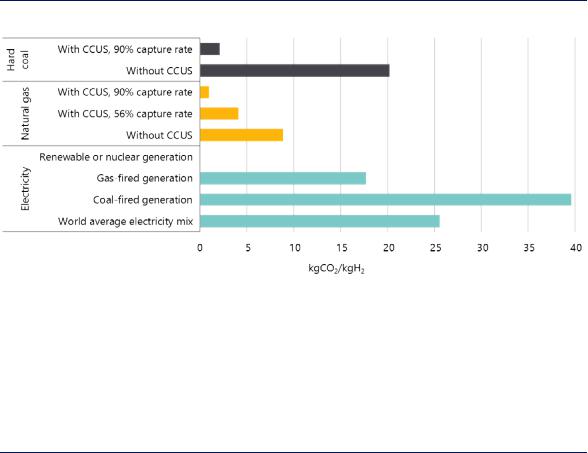
The CO2 impact of different hydrogen production technologies varies widely (Figure 17). The carbon intensity of hydrogen from natural gas without CCUS is roughly half that of coal without CCUS. The CO2 intensity of electrolysis depends on the CO2 intensity of the electricity input. The conversion losses during electricity generation mean that using electricity from natural gas or coal power plants would result in higher CO2 intensities than directly using natural gas or coal for hydrogen production. This means that for electrolysis to have the same or lower CO2 intensity as hydrogen production from natural gas without CCUS, the CO2 intensity of electricity has to be below 185 grams of carbon dioxide per kilowatt hour (gCO2/kWh), just above half the emissions of a modern combined-cycle gas power plant.
Figure 17. CO2 intensity of hydrogen production
Notes: Capture rate of 56% for natural gas with CCUS refers to capturing only the feedstock-related CO2, whereas for 90% capture rate CCUS is also applied to the fuel-related CO2 emissions; CO2 intensities of electricity taking into account only direct CO2 emissions at the electricity generation plant: world average 2017 = 491 gCO2/kWh, gas-fired power generation = 336 gCO2/kWh, coalfired power generation = 760 gCO2/kWh. The CO2 intensities for hydrogen also do not include CO2 emissions linked to the transmission and distribution of hydrogen to the end users, e.g. from grid electricity used for hydrogen compression. More information on the underlying assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
The CO2 intensity of hydrogen directly from natural gas is half of that from coal and nearly half that from gas-fired electricity; the CO2 intensity of electrolysis depends on the CO2 intensity of the electricity.
Low-carbon hydrogen produced with CCUS or from renewable electricity is in most cases currently more costly than hydrogen generated from unabated fossil fuels. The cost of hydrogen produced from natural gas is generally around USD 1.5–3/kgH2, while for hydrogen generated from renewable electricity (solar PV or onshore wind) it is generally around USD 2.5–6/kgH2. Making hydrogen from natural gas with CCUS in the Middle East competitive with unabated fossil fuel hydrogen production would require a CO2 price of around USD 50/tCO2, or an equivalent cost benefit for the CCUS option.
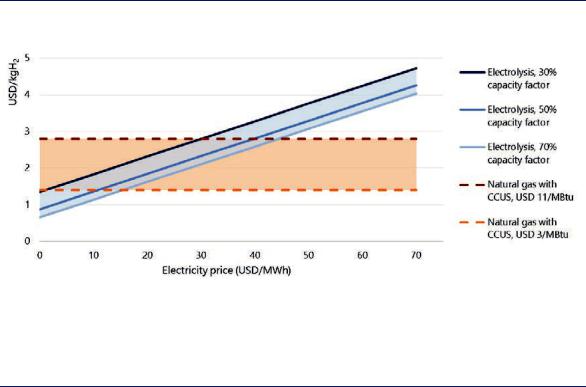
The future competitiveness of low-carbon hydrogen produced from natural gas with CCUS or from renewable electricity (from solar PV or onshore wind) mainly depends on gas and electricity prices. At low gas prices, renewable electricity must reach a cost range below USD 10/MWh for electrolysis to become cost-competitive with natural gas with CCUS. Higher gas prices would make higher-cost renewable electricity cost-competitive: at a gas price of USD 11/MBtu, renewable electricity would be competitive at up to around USD 30–45/MWh (Figure 18).
PAGE | 53
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 2: Producing hydrogen and hydrogen-based products |
Figure 18. Comparison of hydrogen production costs from electricity and natural gas with CCUS in the near term
Notes: More information on the underlying assumptions is available at www.iea.org/hydrogen2019.
Source: IEA 2019. All rights reserved.
Depending on local gas prices, electricity at USD 1040/MWh and at full load hours of around 4 000 hours are needed for water electrolysis to become cost-competitive with natural gas with CCUS.
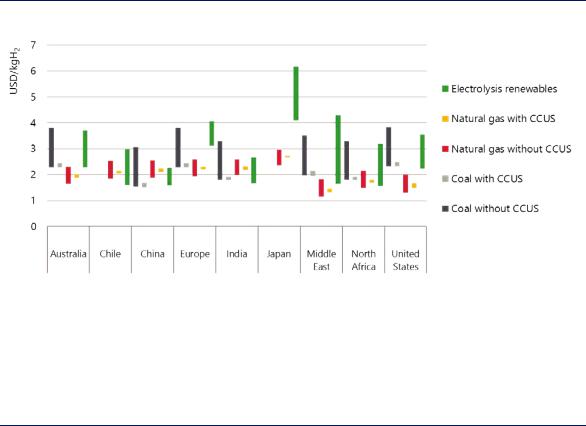
The impact of renewable electricity and gas costs on hydrogen production costs becomes apparent when looking at specific countries (Figure 19). In countries with good renewable resources, but dependent on natural gas imports, in particular in the form of liquefied natural gas, producing hydrogen from renewables may be cheaper than producing it from natural gas, while production from natural gas with CCUS may be the cheaper option in regions with cheap domestic gas resources and CO2 storage availability.
Other factors are also relevant to the choice between alternative low-carbon hydrogen production options. For hydrogen production from fossil fuels in combination with CO2 storage, the geological availability and public acceptance of CO2 storage are prerequisites. For water electrolysis, access to adequate supplies of water is a prerequisite, even if the costs for water treatment (e.g. seawater desalination) are only a small fraction of the total hydrogen production costs. Countries could also consider importing hydrogen or hydrogen-based products if they are available at a lower price than domestic alternatives, as discussed in more detail in Chapter 3.
From an investment viewpoint, the scale of investment is also relevant. While CCUS plants require a certain scale to justify the investment in CO2 transport and storage infrastructure, electrolysers operate at a smaller scale using more modular technology, which can be gradually expanded and adjusted to demand. For example, the H21 North of England project in the UK plans to produce hydrogen from twelve ATR units with CCUS, each with a capacity of around 1 350 MWH2 and requiring an investment of around USD 945 million per unit, whereas the largest electrolyser module offered today is 20 MWe (14 MWH2), requiring investment of around USD 18 million (or USD 280 million for 220 MWH2).
PAGE | 54
IEA. All rights reserved.
The Future of Hydrogen |
Chapter 2: Producing hydrogen and hydrogen-based products |
Figure 19. Hydrogen production costs in different parts of the world
Notes: Bars indicate range between nearand long-term hydrogen production costs, which include a CO2 price of USD 25/t CO2 in the near term and USD 100/tCO2 in the long term. For options from coal and natural gas, the higher value indicates the long-term costs (due to the increasing CO2 price), whereas for hydrogen from renewable electricity the lower value indicates the long-term costs.
Source: IEA 2019. All rights reserved.
In countries relying on gas imports and characterised by good renewable resources, clean hydrogen production from renewable electricity can compete effectively with production that relies on natural gas.
Converting hydrogen to hydrogen-based fuels and feedstocks that are easier to store, transport and use
Hydrogen has low energy density, which makes it more challenging to store and transport than fossil fuels. However, it can be converted into hydrogen-based fuels and feedstocks, such as synthetic methane, synthetic liquid fuels and ammonia, which can make use of existing infrastructure for their transport, storage and distribution. This can reduce the costs of reaching final users. Some of the synthetic hydrocarbons produced from hydrogen can be direct substitutes for their fossil equivalents. Ammonia is already used today as a feedstock in the chemical industry (see Chapter 4) and could be a hydrogen carrier for the long-distance transport of hydrogen in the future (see Chapter 3), or itself be used as fuel in the shipping sector (see Chapter 5).
The potential benefits and opportunities of these hydrogen-based fuels and feedstocks have to be weighed, however, against the costs of converting hydrogen into these products. Many of the technology pathways to produce these fuels and feedstocks are at an early demonstration stage, resulting in high costs. Producing ammonia requires the separation of nitrogen from the air, while the production of synthetic hydrocarbons requires carbon as an input, which has implications for the cost of production, while the origin of the carbon also affects the environmental impact and the carbon intensity of the synthetic hydrocarbon.
PAGE | 55
IEA. All rights reserved.